Many health plans, including Medicare and Blue Cross Blue Shield, cover chiropractic care, but your out-of-pocket costs depend on your copay, deductible, and whether your chiropractor is in-network. Knowing these terms before you book helps you avoid surprise bills.
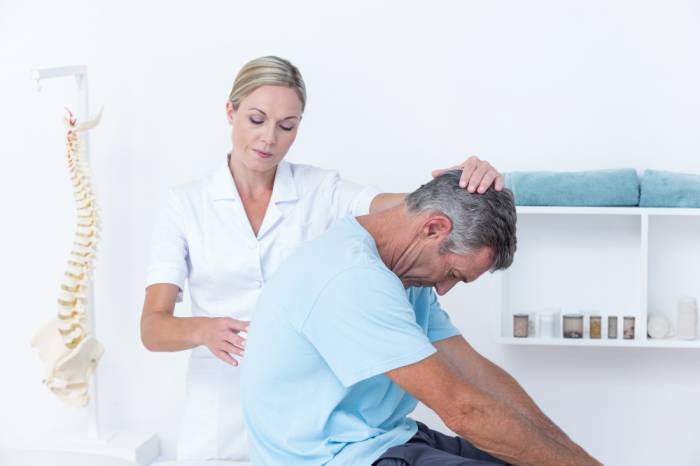
Back pain is the leading cause of disability worldwide, and untreated symptoms often worsen over time. Chiropractic treatment offers a conservative, drug-free option for spinal pain, headaches, and mobility problems, making it an attractive first step for many patients before more invasive interventions.
Research has linked chiropractic care to positive patient outcomes and lower overall healthcare costs, which is why Medicare beneficiaries and private insurers continue to expand access to these services. The sections below explain what BCBS and Medicare typically do—and do not—cover, how copays work, and what your deductible means for your wallet.
What Does Blue Cross Blue Shield Chiropractic Coverage Exclude?
Blue Cross Blue Shield (BCBS) plans vary by state and policy, but most exclude certain chiropractic services even when basic spinal manipulation is covered. Knowing these exclusions before your appointment helps you avoid surprise bills and plan affordable treatment for back pain, neck pain, and other musculoskeletal conditions.
Common Chiropractic Services BCBS May Not Cover
While BCBS covers chiropractic treatment for many patients, typical policies exclude or limit coverage for the following:
- Maintenance or wellness care intended to prevent future problems rather than treat an active condition
- Services from out-of-network providers, which usually require higher out-of-pocket costs or full self-payment
- Diagnostic imaging such as X-rays or MRIs ordered by a chiropractor, unless pre-approved
- Massage therapy, nutritional counseling, or acupuncture offered in a chiropractic office
- Treatment beyond a set number of covered visits per year, with limits that vary by plan
Deductibles, Referrals, and Prior Authorization
Even covered services may require you to meet your annual deductible before BCBS begins paying its share. Some policies also require a referral from your primary care physician or prior authorization before your first chiropractic visit. Failing to obtain these approvals can turn a covered visit into an out-of-pocket expense.
How to Make Chiropractic Care More Affordable
If your BCBS plan offers limited chiropractic benefits, several options can reduce your costs:
- Check whether a supplemental health insurance plan covers chiropractic visits or helps with copays and deductibles
- Ask your chiropractor about sliding-scale fees or interest-free payment plans
- Confirm your chiropractor is in-network to take advantage of negotiated rates
- Review your policy documents or call the member support number on your BCBS card to verify coverage details before scheduling
Chiropractic care remains an effective, conservative treatment for back pain, neck pain, headaches, and injury-related discomfort. Understanding your BCBS policy’s exclusions, deductible, and referral rules helps you receive the care you need without unexpected costs.
Understanding Chiropractic Copays and Out-of-Pocket Costs
A copay (or copayment) is a fixed dollar amount you pay at the time of a chiropractic visit or other covered healthcare service. Your copay is separate from your monthly insurance premium and counts toward your plan’s annual out-of-pocket maximum. Unlike a deductible, which you must satisfy before most coverage begins, a copay is typically due at each appointment, though the exact timing depends on your policy.
For example, a Blue Cross Blue Shield plan might charge a $30 copay for an in-network chiropractic adjustment. That amount goes toward your yearly out-of-pocket limit, which is the most you’ll pay for covered in-network care in a plan year. Your out-of-pocket maximum usually combines your deductible, copays, and coinsurance.
To keep costs predictable, always verify that your chiropractor is in-network. A network is a group of doctors and providers who have agreed to accept your insurance plan’s negotiated rates, such as the providers included in Humana Medicare Advantage plans 2025. An out-of-network chiropractor hasn’t agreed to those rates and may bill you for the difference, often at a higher price. Checking your coverage before booking an appointment helps you avoid surprise bills and stay within your plan’s limits.
Copay amounts vary by plan and provider. Some plans require a referral from your primary care physician before chiropractic care is covered, and others apply a separate chiropractic benefit with its own copay and visit limits. Reviewing your policy documents or calling member support can clarify exactly what you’ll owe at each visit.
What Is a Health Insurance Deductible?
A health insurance deductible is the fixed amount you pay out of pocket each plan year before your insurer starts covering eligible medical costs. For chiropractic care, that means you typically pay the full cost of your first visits — including spinal adjustments — until your annual deductible is met. Only after that point does your plan’s coinsurance or copay structure take over.
Deductibles are separate from copays, which are flat fees charged at the time of service, and coinsurance, which is a percentage of the bill you share with your insurer after meeting your deductible. Understanding this distinction matters when you’re budgeting for regular chiropractic treatment under a Blue Cross Blue Shield policy.
How Your Deductible Affects Chiropractic Visit Costs
Your deductible directly shapes what you pay for each chiropractic session. Before it’s met, you’re responsible for the full negotiated rate of your adjustment, evaluation, and any therapies your chiropractor provides. Once you reach the deductible, BCBS begins covering its share, and you’ll typically pay only your copay or coinsurance for each visit.
High-Deductible Plans: A Trade-Off to Consider
High-deductible health plans (HDHPs) offer lower monthly premiums in exchange for a higher annual deductible. They can be a smart fit if you’re generally healthy and seldom use medical services. However, if you depend on ongoing chiropractic care for back pain relief or posture improvement, an HDHP may leave you covering many sessions at full price before your coverage activates.
Some employer-sponsored plans let you pair an HDHP with a personal health account (PHA). Funds in a PHA can be applied toward chiropractic visits and other qualified medical expenses, softening the financial impact of a high deductible.
Deductibles Reset Every Plan Year
Your deductible and out-of-pocket maximum reset on your plan’s renewal date each year. Progress toward meeting your deductible never carries over. When comparing BCBS plans, weigh the deductible amount against your expected number of chiropractic visits to confirm you can comfortably manage both your monthly premium and your annual out-of-pocket costs.